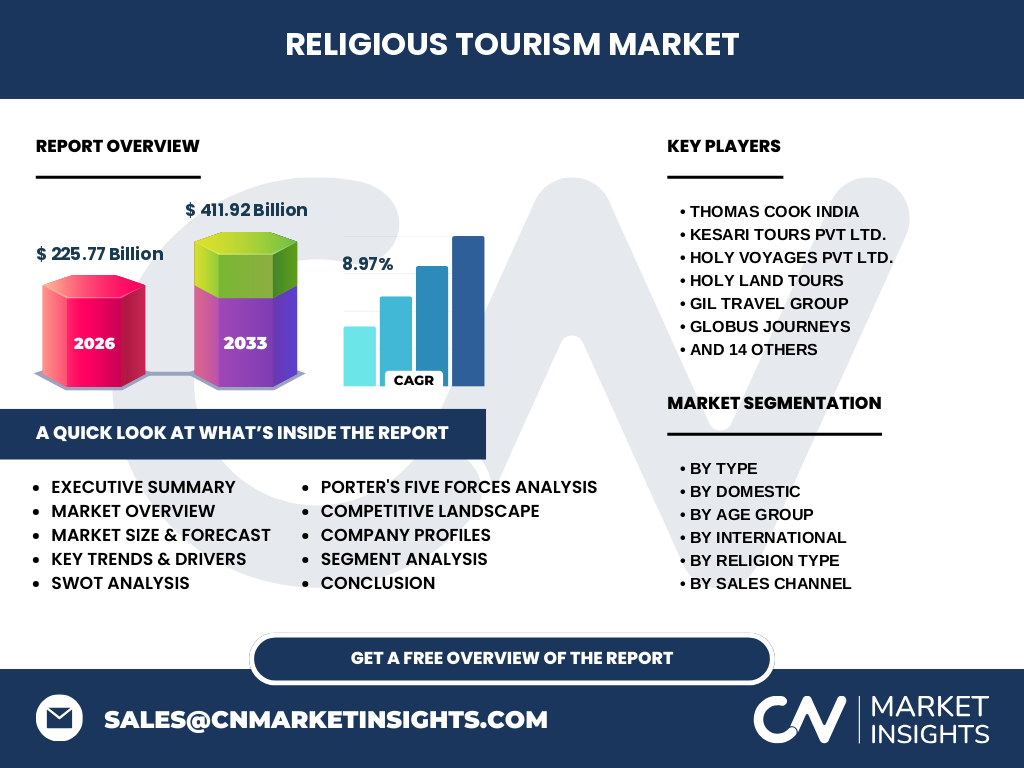
Market overview of the Religious Tourism Market
Our analysis indicates that the Religious Tourism Market achieves a valuation of 225.77 Billion in 2026. This sector encompasses structured spiritual travel, sacred site expeditions, and faith-based pilgrimages globally, governed by strict cultural protocols and specialized visa regulations.
Structural Growth Drivers and Restraints
The market is propelled by a 8.97% CAGR, driven by rising disposable incomes and digital booking integration. However, infrastructure bottlenecks in remote sacred locations and stringent border controls by ministries of religious endowments act as notable logistical restraints.
Emerging industry trends in the Religious Tourism Market
The sector experiences a profound shift toward digitized itinerary curation and eco-sustainable sacred travel. Operators like Thomas Cook India and Kesari Tours Pvt Ltd. increasingly leverage mobile applications to streamline chaotic foot traffic during peak seasonal festivals.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted sanctuary access, forcing a rapid pivoting toward virtual pilgrimages. The subsequent recovery trajectory showcases robust pent-up demand, with international corridors reopening under strict biosecurity protocols managed by global health authorities.
Competitive Benchmarking and Market Concentration
Competitive intensity is high, characterized by a mix of specialized operators and diversified travel giants. Firms like Holy Voyages Pvt Ltd. and Holy Land Tours compete fiercely by securing exclusive lodging allocations near high-density religious centers.
Executive summary of key findings
This report synthesizes that the Religious Tourism Market industry trends point toward exponential expansion, targeting a staggering 411.92 Billion by 2033. Strategic adaptability in online booking channels remains the primary differentiator for market leaders.
Market forecast from 2027 to 2033
Driven by robust demographic shifts and expanding aviation routes, the market is projected to scale from its baseline to 411.92 Billion by 2033. This trajectory reflects sustained compound annual growth of 8.97% across developing economies.
Segmentation analysis across core categories
Segmentation spans Type (Domestic, International), Age Group (Below 30 to Above 50 Years), Religion Type (Buddhism, Catholicism, Confucianism, Hinduism, Islam, and Others), and Sales Channels (Offline, Online). Each category dictates specialized logistical requirements and localized ground handling partnerships.
Geographic distribution and regional market analysis
Regional performance varies significantly based on sacred geography and state-sponsored tourism initiatives. Asia-Pacific dominates domestic pilgrimage volumes, whereas transatlantic corridors heavily influence international Catholic and Islamic pilgrimage numbers handled by agencies like Gil Travel Group.
In-depth regional review of the Religious Tourism Market
Our research details dense pilgrimage circuits across South Asia and the Middle East, contrasting with aging demographic participation in Western Europe. Localized municipal constraints and heritage preservation laws heavily dictate regional expansion paces for operators such as Globus Journeys.
Strategic positioning of leading companies
Key market participants such as 206 Tours, Nativity Pilgrimage, and Regina Tours command strong footholds via specialized Christian itineraries. Meanwhile, agencies like AlHaramain Tours and Al Madina Tour Services capture substantial market share through localized Hajj and Umrah expertise.
Porter's Five Forces analysis of the sector
Bargaining power of buyers remains moderate due to abundant agency choices, while supplier power—specifically boutique hoteliers near shrines—is high. Threat of substitutes is mitigated by the irreplaceable cultural authenticity offered by established organizers like Marian Pilgrimages.
SWOT analysis of the Religious Tourism Market
Core strengths include deeply ingrained cultural motivations and high repeat-customer rates. Weaknesses involve seasonal volatility, while opportunities lie in digitalization; threats stem from geopolitical instabilities near sensitive border-adjacent religious sites.
Value chain analysis and industry structure
The value chain flows from raw localized transport and accommodation providers through specialized tour operators like Dynamic Catholic Pilgrimages and Radiant Tours, culminating in direct consumer delivery via offline agencies or online travel portals.
Strategic investment insights for stakeholders
High-potential areas include digital B2B booking platforms and eco-friendly hospitality infrastructure near rural shrines. Investors should prioritize agencies demonstrating strong regulatory compliance and established ground-handling networks in emerging Asian and Middle Eastern markets.
Conclusion and core takeaways
The Religious Tourism Market analysis proves that faith-based travel is recession-resilient and technologically evolving. Reaching 411.92 Billion by 2033 requires operators to blend traditional reverence with modern digital convenience seamlessly.
Proprietary research methodology
Our baseline estimates are rigorously triangulated by combining trade registry data from ministries of tourism, primary stakeholder interviews with executives from Royal Vacations and Pilgrimage Tours, and secondary macroeconomic indicators regarding global discretionary spending.
Scope and limitations of the report
This assessment covers global Religious Tourism Market market size dynamics from 2026 to 2033. Limitations include potential data opacity in informal, cash-dominant local shrine economies and unpredictable shifts in geopolitical travel restrictions.
Recent developments, partnerships, and strategic moves
Recent industry momentum features aggressive tech-adoption by firms like Aladdin Tours and Travel and Abraham Tours, alongside strategic airline partnerships forged by Shiv Shankar Tirth Yatra and Akbar Holidays to secure guaranteed charter slots for mega-festivals.